All Categories
Featured
Table of Contents
The APR is the expense of credit as a yearly rate and reflects both your rates of interest and an origination charge of 0.99%9.99% of your loan amount, which will be deducted from any loan continues you receive. The origination fee on a loan term 4 years or longer will be at least 4.99%.

Eligibility for the very best offered rate subject to credit reliability. : a 5-year $10,000 loan with a 9.99% APR has actually 60 scheduled regular monthly payments of $201.81; a 3-year $5,000 loan with 6.99% APR has actually 36 scheduled month-to-month payments of $152.83. Finest Egg loans can be prepaid at any time without charge.
To help the government battle the funding of terrorism and cash laundering activities, Federal law requires all banks to acquire, validate, and record information that identifies each individual who opens an account. What this means for you: When you open an account, we will request your name, address, date of birth, and other details that will enable us to recognize you.
Secrets to Negotiating With Major Lenders in South CarolinaFinest Egg loans are individual loans made by Cross River Bank, a New Jersey Chartered Bank, running from its Wilmington, Delaware branch location, Member FDIC, Equal Housing Lender, or Column N.A., Member FDIC, Equal Housing Lending Institution. 2026 Marlette Marketing, LLC. All rights scheduled.
Complimentary debt consolidation programs are normally used by not-for-profit credit counseling companies that help combine numerous financial obligations into one monthly payment. These programs typically reduce rate of interest and waive costs, making it much easier to settle unsecured debt within three to five years."Free" generally refers to the preliminary credit therapy session, while continuous debt management strategies might include small regular monthly costs.
Best Debt Relief Programs for 2026
Working with a certified nonprofit firm can assist guarantee transparent charges, genuine services and a structured path to ending up being debt totally free. Financial obligation consolidation integrates high-interest charge card bills into a single monthly payment at a minimized interest rate. Paying less interest saves cash and enables you to settle the debt quicker.
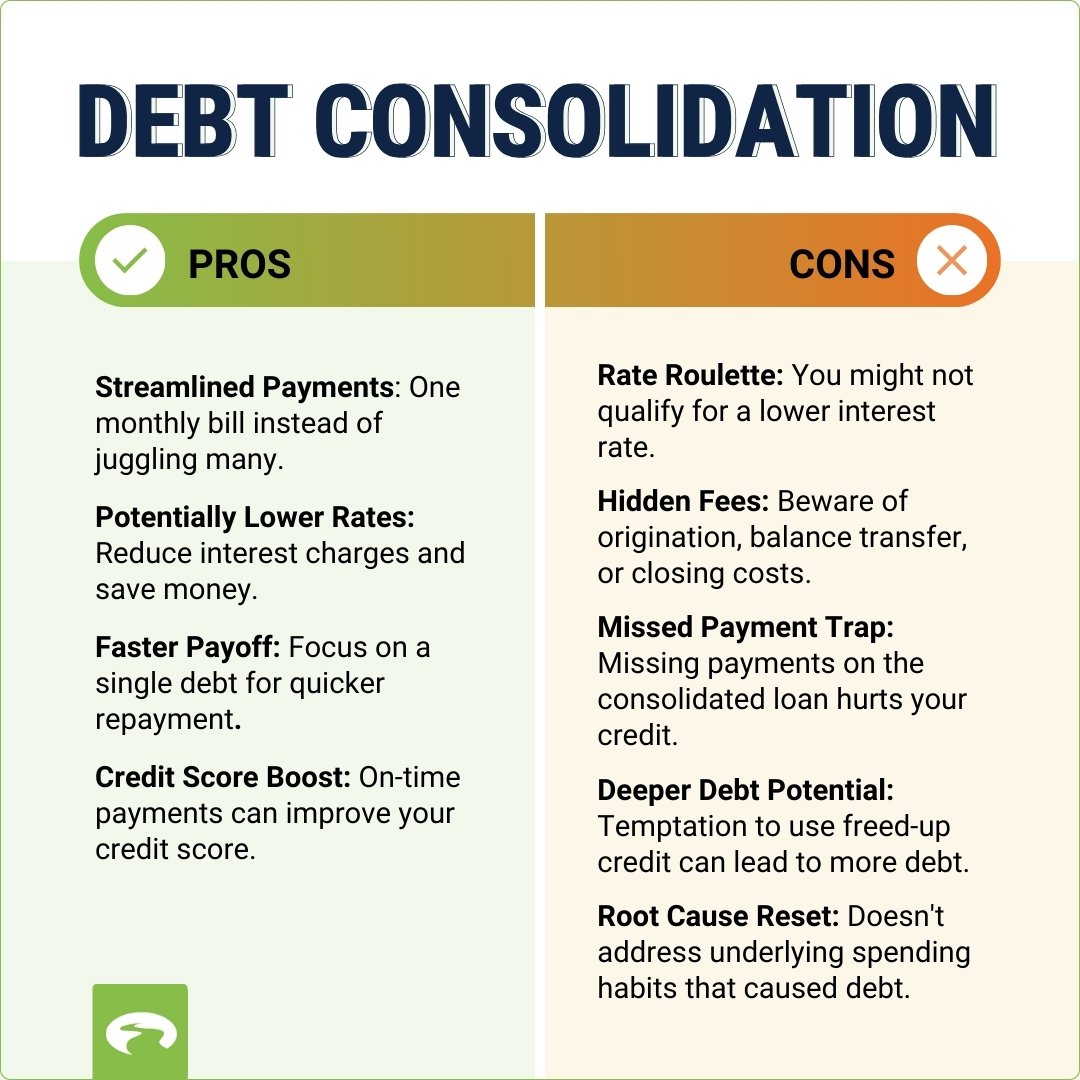
, either through a financial obligation management plan, a debt consolidation loan or financial obligation settlement program.
, call a not-for-profit credit therapy company like InCharge Financial obligation Solutions. A qualified therapist will go through your income and expenditures, assist you develop a budget-friendly regular monthly spending plan, then use complimentary advice on which consolidation program will eliminate your debt.
A Step-By-Step 2026 Financial Hardship Guide
"When you're in debt, you need to comprehend your budget, what it's going to take to solve your debts and how you can put reasonable, inexpensive payments in location to achieve that goal. These programs are used by nonprofit credit therapy agencies, who work with credit card companies to show up at a lower, more cost effective monthly payment for you. Nonprofit debt consolidation is the truest form of a financial obligation combination program.
Secrets to Negotiating With Major Lenders in South CarolinaYou have the backing of a nonprofit business with credit counselors to respond to concerns and guide you through challenging monetary circumstances. This is not a loan and your credit report is not a factor in qualifying. Reduced rates of interest (somewhere around 8%, sometimes less) assist lower regular monthly payments. Credit counselors help in establishing an economical month-to-month budget plan.
Does Debt Management Improve the Credit Future?
If you miss out on a month-to-month payment, all concessions given by the financial institution could be canceled. There is a one-time setup fee between $50-$99 along with a regular monthly service charge balancing $34, but the savings on interest should more than offset the charges. You are required to stop utilizing charge card other than for one emergency card.
License the company to access a list of your charge card financial obligations and month-to-month payment info from your credit report. Collect info about your regular monthly income and costs to determine just how much money you have offered for charge card combination. Be prepared to address concerns about your objectives and the timeline you're working toward to become financial obligation free.

Latest Posts
Will Debt Consolidation Right Choice in 2026?
Choosing Professional Debt Management Providers in 2026
Managing Mounting Household Liabilities With Strategic Methods